What decides the interest rate on a personal loan: credit score, income, existing debt and tenure
Two borrowers seeking the same amount can be offered different rates, as lenders weigh risk and repayment capacity, and the rate alone is not the full cost.
 Images are not validated/verified
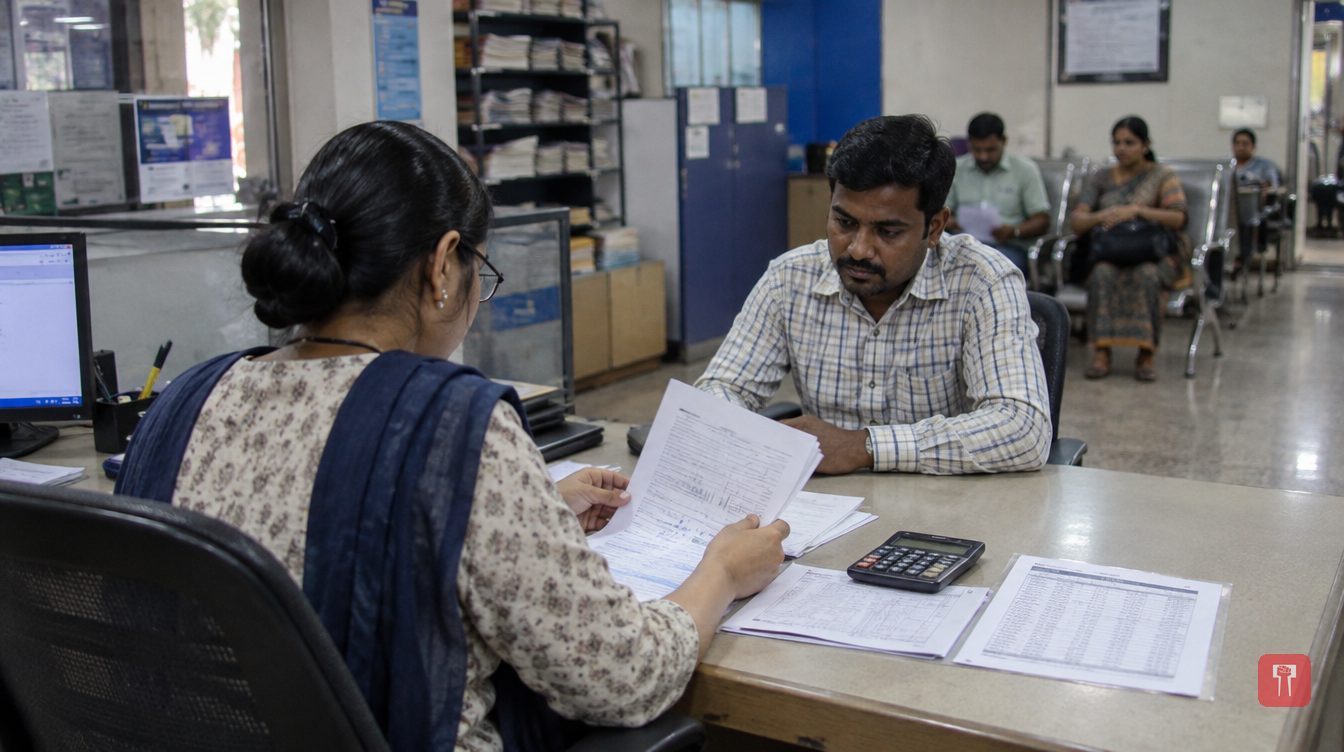
Every borrower applying for a personal loan does not get the same interest rate. Even two people asking for the same amount can be offered different rates, because banks and other lenders assess each person's risk, repayment capacity and some other factors separately.
Once you understand what the rate depends on, it becomes easier to estimate the cost of a loan before choosing one. Lenders generally look at several aspects of your financial position to set the rate.
The first is the credit score and past repayment record. This tells the bank how you handled earlier loans. A record of paying instalments on time and using credit sensibly can strengthen a profile. A weak or short credit history does not automatically mean rejection, but it can affect the terms on offer. It can therefore help to check your credit report before applying.
The second is income and job stability. The bank looks at whether your income can sustain a new EMI along with existing obligations. Regularity of salary, job history and the nature of employment can therefore also affect the rate. Self-employed applicants may be assessed on income documents and other financial information related to their business and repayment capacity.
The third is existing loans and liabilities. If you already have several loans or credit commitments, the bank may look at your total debt burden before fixing the rate. With fewer liabilities, there may be considered to be more room for another EMI. Before taking an instant personal loan, do not look only at how quickly the money will reach your account; check your current EMIs and monthly expenses too.
The fourth is the loan amount and the repayment tenure. A longer tenure can make the EMI smaller, but the interest paid over the life of the loan can rise. Do not decide on the advertised rate alone; compare the total amount to be repaid.
Is the rate on an instant personal loan always higher? Not necessarily. The speed of approval or disbursal does not by itself determine the interest rate. Instant loans may use digital verification and automated credit checks to speed up processing, while the price still rests on the bank's assessment of the borrower.
As an example, IDFC FIRST Bank's FIRSTmoney personal loan is offered through a digital process, with interest rates starting at 9.99% p.a. However, the actual rate depends on factors such as credit profile, income, job stability and existing liabilities.
The interest rate is not the whole cost. Before accepting an offer, compare the processing fee and applicable taxes, the tenure and EMI, foreclosure or prepayment terms, penal charges for late payment, whether the rate is fixed or floating, and, where applicable, the annual percentage rate (APR).
For floating-rate EMI-based personal loans of the relevant kind, RBI rules say lenders must explain the impact of changes in the benchmark rate and inform the borrower about rate resets.
On the whole, the interest rate on a personal loan is generally set not by any single factor but by separate assessments of risk and repayment capacity. Credit history, income, employment, existing liabilities, and the loan amount and tenure can all affect the final offer. Whether taking a traditional personal loan or an instant one, compare the full cost of borrowing and read the applicable terms before accepting an offer.
A question often asked is whether a high credit score guarantees low interest. The answer is no. A strong credit profile can help in getting a better rate, but the final rate depends on the bank's overall assessment. Similarly, choosing a longer tenure does not necessarily lower the interest rate. It can reduce the monthly EMI, but the total interest can rise.
